Read Time:
Permanent Establishment Risk When Hiring Abroad: What Indian Companies Should Know

Permanent establishment risk is the chance that hiring people abroad gives a foreign tax authority grounds to say your Indian company has a taxable business presence there, even though you never set up an entity. It usually comes from what overseas staff do (signing contracts, setting prices, working only for you), not from their job titles.
| Situation abroad | PE risk signal | Safer practice |
|---|---|---|
| Overseas hire negotiates or signs customer contracts | High: classic dependent-agent pattern | Keep signing authority in India; staff only introduce and relay |
| Local staff set or change prices | High | Pricing approved outside the country and recorded in writing |
| Employee works only for you from a home office | Medium to high: possible fixed place | Review with tax counsel; consider an EOR or entity |
| Independent contractor working like an employee | Medium to high | Check local law on contractor status before engaging |
| Service team staying in-country for long periods | Medium: possible service PE | Track days and duties; seek advice before extending |
| Single hire through an EOR, no sales authority | Lower, but not zero | Written role limits and counsel sign-off |
Accidental permanent establishment risk is the chance that an overseas hire creates a taxable presence for your company without anyone planning it. It happens when local tax authorities decide that your employee's activities, such as concluding contracts or working from a fixed place, amount to your company doing business in that country.
A permanent establishment, or PE, is the tax concept that lets a country tax a foreign company's profits earned locally. The usual forms are a fixed place of business, a dependent agent who habitually concludes or negotiates contracts, and a service PE where your people deliver services in-country for a sustained period.
The word "accidental" matters. The pattern is common: a company thinks it is working offshore on a limited basis, and local authorities conclude the scale or nature of the work is a taxable presence.
Indian mid-market firms going global rarely start with a subsidiary. They place one sales lead in Singapore, a country manager in Japan, an engineer in Germany. Each hire is sensible alone. Together they can add up to a business presence that nobody on the finance side ever reviewed.
Titles hide the issue. A "business development manager" who is told to close deals locally looks, to a tax inspector, like a dependent agent. A "consultant" who sits at the same home desk for two years and takes instructions only from India looks like an employee with a fixed place.
CBREX has completed more than 50 country manager or head-of-market placements, including one in Japan. Those roles are exactly where PE risk concentrates, because the whole point of hiring a country manager is that someone local represents the company to customers. The hire is right; the authority you hand over is what needs a rule.
Tax authorities in India itself are active on this question. Indian courts have heard disputes over taxable presence, and the law on those points may still be moving. Anyone hiring into India or out of it should expect the position to keep moving.
The main warning signs are staff who sign or negotiate contracts locally, staff who set prices, an employee who works only for your company with no independent business, a home or office space you effectively control, and people who stay in-country on service work for long stretches. Any one sign warrants a tax counsel check.

This is the sign that appears in most tax guidance. University tax guidance on mitigating PE exposure points to whether the individual has the authority to conclude contracts on behalf of the home company, as Cornell's tax materials describe it.
In practice, check three things. Who signs customer or partner contracts? Who agrees the final commercial terms? Does the overseas hire say "yes" to deals, or "I will take that back to the team in India"? The second answer is the safer one.
A hire who can quote, discount and close without approval from India behaves like a local sales office. Set a written pricing approval path. Keep records of each approval, with the date and the approver's location.
An employee who works only for you, takes day-to-day direction from India and works from a home office or a desk you pay for can raise a fixed-place question. Fixed place of business and service activity are commonly treated as separate triggers, so check each when you hire abroad.
Sending Indian engineers or consultants to deliver work in another country for extended periods can create a service PE in some treaties. Track days on the ground, the tasks performed and who the customer is. If the stay keeps getting extended, ask counsel before the next extension, not after.
Independent contractors can cut payroll and HR admin, but Stanford's global business guidance flags the need to confirm the individual is legally able to provide those services in the country. A contractor with fixed hours, one client and daily instructions can look like an employee in law, whatever the invoice says.
Use a local entity when you plan a lasting, growing team with sales or operational authority in one country. Use an employer of record when you have one to a few hires and want local employment without an entity. Use an agency to find the candidate. Agencies source talent; they do not replace the employment structure.
Each route solves a different problem, so comparing them as if they were substitutes causes errors. The table sets them side by side.
| Route | What it does | Best for | Watch out for |
|---|---|---|---|
| Own local entity | Your company becomes the registered local employer and taxpayer | Scaled teams, sales authority, long-term plans | Set-up time, ongoing compliance, local filings |
| Employer of record (EOR) | A third party legally employs the person; you direct the work | One to a few hires, market testing | Does not find the person; does not make PE risk vanish if the hire concludes contracts for you |
| Recruitment agency or marketplace | Finds, screens and presents candidates | Sourcing in any country | Still need to decide who employs the hire |
| Contractor | Person invoices you as an independent business | Genuine project work | Misclassification if they work like an employee |
If the hire will sign, negotiate or price on your behalf, go to counsel before the offer and expect to need a local entity or a carefully scoped structure. If the hire is an engineer, analyst or support role with no contracting authority, an EOR with written role limits is usually the lighter route.
If the team in one country grows past a few people, or someone becomes the de facto local head, reassess. At that point the cost of an entity is often smaller than the cost of arguing a PE assessment later. That is a judgement call, not a statutory threshold; no single headcount number settles it.
An EOR takes on local payroll, contracts and compliance. CBREX has partners that provide EOR in over 90 countries, so a hire found through the platform can be employed through a partner route where that suits you. Tax authorities can still look at what an EOR-employed person does for you, so an EOR is not a magic shield.
Our own advice: treat an EOR as an employment and compliance tool, not a tax opinion. The question "does this person conclude contracts for us?" has to be answered whatever the payroll structure. For a deeper look at the model, our guide to the CBREX platform walkthrough shows how sourcing and employment routes fit together.
A single-contract agency model solves the sourcing side of overseas hiring: one agreement gives access to specialist recruiting firms in many countries, so you find local talent without opening an entity first. It does not, on its own, settle where the person is employed or taxed. That choice is made separately.
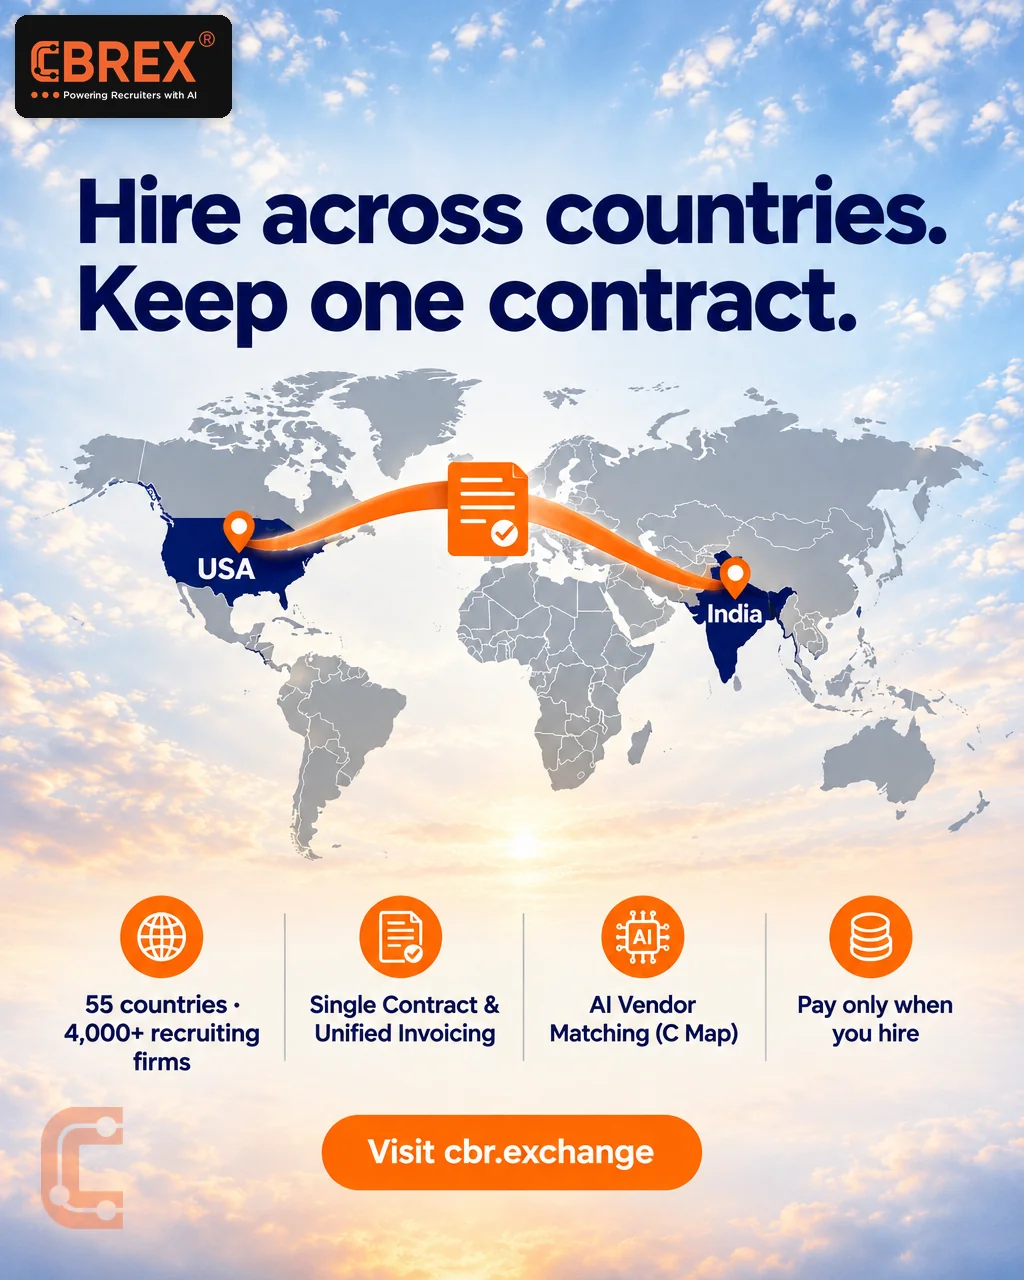
On CBREX, one contract and one invoice cover 4,000+ specialist agencies across 55 countries. You post a role, C Map matches it to the most relevant firms, and you pay only when a hire is made. There are no retainers, seat licences or upfront fees.
Hiring locally means candidates already live and have the right to work in the country. In one Germany search, CBREX went from opening to hire in 30 to 45 days with no visa step, because the candidates were local or EU citizens who could already work there. No relocation of Indian staff means no long-stay Indian secondees on the ground, which removes one common service-PE pattern.
The usual cost range for European placements on the platform is a fee of 15% to 30%, with a notice period typically around 30 days. Replacement guarantees run 30 to 90 days per placement, with a free replacement or refund per eligible claim.
Overseas hiring often means many agencies, many agreements and many places where authority is unclear. One of our clients consolidated 54 agency contracts into a single CBREX contract. A single agreement gives finance one paper trail: who engaged whom, on what terms, signed where. That helps when you need to show tax counsel a clean record.
The platform also checks for duplicate submissions when an agency uploads a candidate, so two agencies cannot submit the same person for one role. It is a sourcing control, not a tax control, and we say so plainly.
PE rules, treaty positions and employment law differ by country. If you are weighing specific markets, start with our handbooks for hiring in japan for indian companies the 2026 handbook
Documents are your best defence if an authority questions your presence. They show intent and limits. They cannot rescue a role that, in reality, does something different. Align the paper with the daily work, and revisit it when the job changes.
If a check fails, do not hire yet. Narrow the role, move the approval to India, switch to an EOR, or plan an entity. Fixing a brief costs a conversation; fixing an assessment costs far more.
Many GCC heads and Indian HR teams write a hiring brief that wants top talent but does not benchmark pay against the local market. Salary benchmarking is a sourcing problem, not a tax one, but it matters here: a brief that is set at market pay lets you recruit a person for the role you actually need, rather than stretching one hire to cover several jobs, including ones that carry contracting authority.
Not by itself. An agency finds and presents candidates; the PE question depends on who employs the person and what the person does for your company afterwards. If the hire negotiates or concludes contracts for you, risk can arise whichever route found them. Confirm your case with tax counsel.
No. An EOR handles local employment, payroll and compliance, but it does not decide what your hire does day to day. If that person concludes contracts for your company, a taxable presence may still be argued. Use an EOR with written role limits and counsel review.
Not automatically. A contractor must be legally able to provide services in the country and must genuinely work as an independent business. One who works fixed hours for you alone can be treated like an employee, with the same PE questions and extra misclassification risk.
No single headcount settles it. Risk depends on activities, authority and how long the presence lasts, under the local law and the relevant treaty. A single person with contracting authority can create more risk than several back-office staff, so review role by role.
Permanent establishment risk is manageable when you decide the structure before the hire, keep contracting authority in India and document the role. This article is general information, not tax advice, so confirm specifics with qualified tax counsel in India and the host country.
For the sourcing side, book a CBREX demo to see how one contract, AI vendor matching and three-level screening work across the countries you are targeting. If you want to talk through a specific market first, email our team and we will help you map the roles, countries and routes before you open a search.
You can also test what slow, fragmented overseas hiring costs you today with the Hidden Hiring Tax calculator.